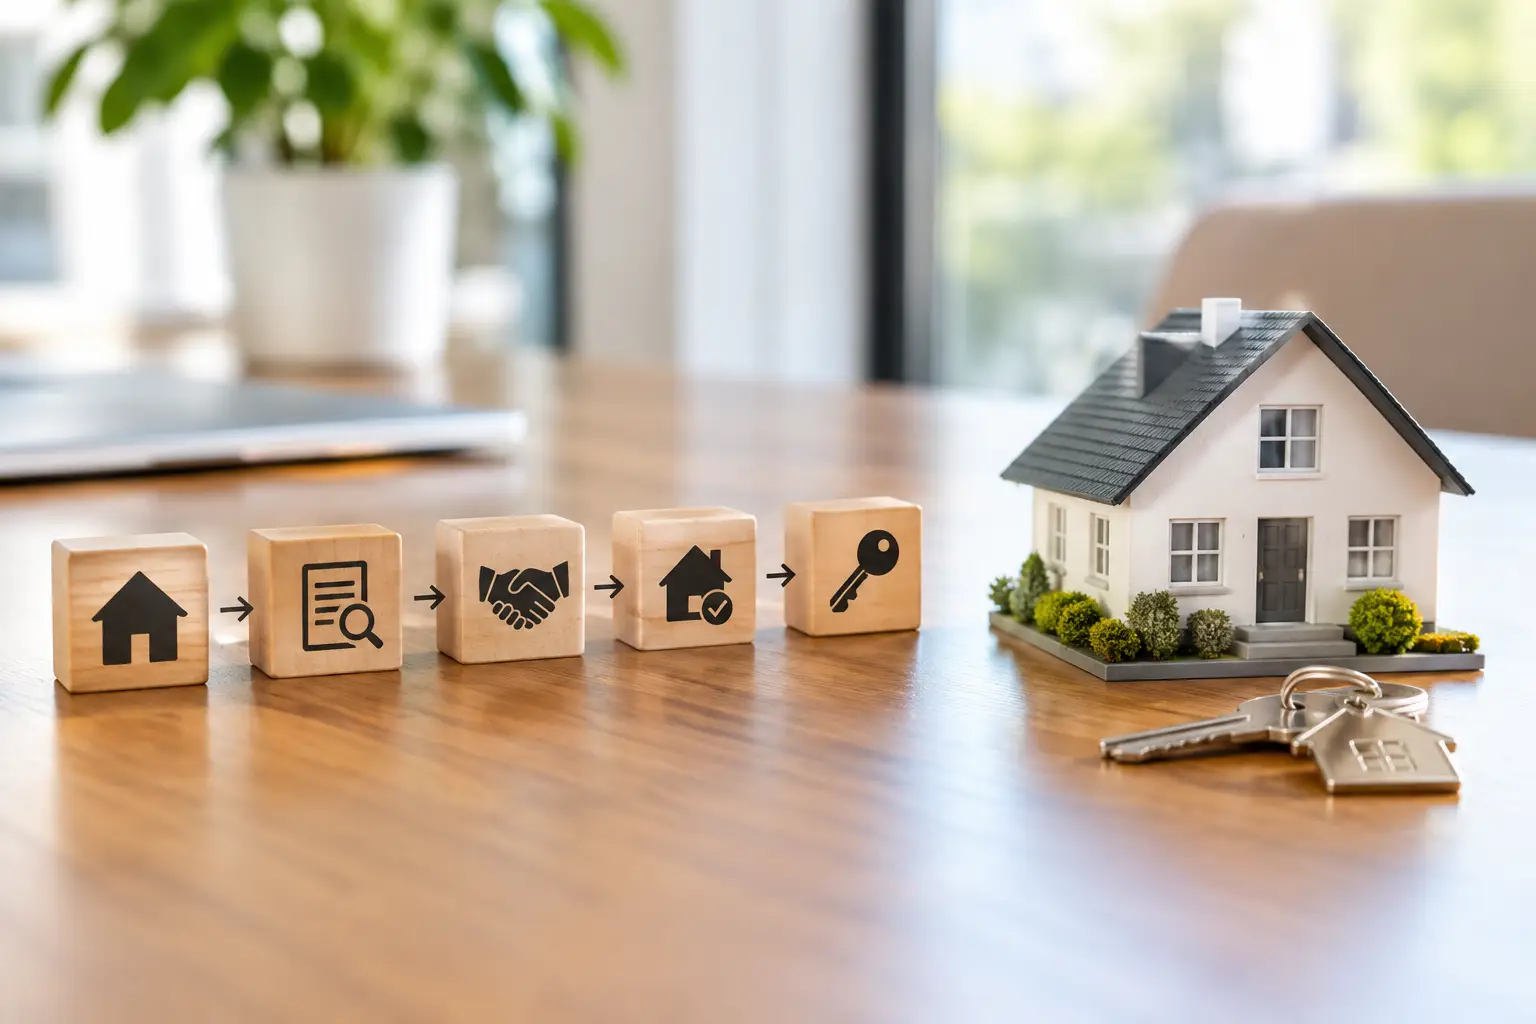
A home sale timeline is not one fixed calendar. A well-prepared home in Beavercreek may attract strong interest in its first weekend, while a property in a rural-edge Miami Valley community may need more time to reach the right buyer. Your price, condition, location, buyer financing, and next move all shape the schedule.
For most Greater Dayton sellers, the process takes roughly six to 10 weeks from active listing through closing after the home is ready for market. Add two to four weeks beforehand for pricing, repairs, cleaning, photography, and launch preparation. Some sales move faster. Others need more time because of inspection negotiations, appraisal issues, buyer lending, or a sale contingency.
How Long Does a Home Sale Timeline Usually Take?
A practical home sale timeline has three parts: preparing the property, marketing and accepting an offer, then moving from contract to closing. The first part is where sellers have the most control. The final part depends on several parties, including the buyer, lender, title company, appraiser, inspectors, and both agents.
A cash buyer can sometimes close in two to three weeks once title work is clear. A financed purchase commonly closes in about 30 days, though 35 to 45 days may make more sense when the buyer needs extra time for underwriting, a complex appraisal, or the sale of another property.
Trying to force every sale into the shortest possible window can create unnecessary stress. The better goal is a realistic schedule that supports strong marketing, protects your negotiating position, and gives you enough time to plan your move.
Two to Four Weeks Before Listing: Price and Prepare
The listing process should begin with an honest pricing strategy, not a guess based on a nearby asking price. A comparative market analysis reviews recent sales, active competition, pending homes, condition, location, lot characteristics, and buyer demand in your specific area.
That local context matters across the Miami Valley. A home near downtown Centerville, a newer property in Springboro, a historic Dayton neighborhood home, and a house convenient to Wright-Patterson Air Force Base can appeal to different buyer groups. The right list price reflects what buyers are actually paying for comparable homes, not just what sellers hope to receive.
Decide What to Repair and What to Leave Alone
Not every home needs a full renovation before it goes on the market. Focus first on issues that may affect buyer confidence, inspections, financing, or appraised value. Roof concerns, active leaks, electrical defects, HVAC problems, peeling paint, and obvious deferred maintenance deserve attention before cosmetic upgrades.
Then consider presentation. Fresh neutral paint, cleaned flooring, trimmed landscaping, decluttered rooms, and brighter lighting can make a meaningful difference in photos and showings. In many Dayton-area price ranges, a clean, well-maintained home performs better than an over-improved property that cannot recover the cost of its updates.
During this stage, gather useful documents: utility information, receipts for major improvements, warranties, survey records if available, and details on items buyers may ask about. If your home is part of an HOA, request current association documents early. Those small preparations can prevent a last-minute scramble after an offer arrives.
Week One on Market: Launch, Showings, and Feedback
Once the property is ready, professional photography, complete listing details, and accurate MLS exposure put the home in front of active buyers and their agents. The first several days matter because new listings usually receive their highest level of attention early.
Showings may begin immediately, especially for appropriately priced homes in sought-after locations such as Kettering, Mason, Troy, or Beavercreek. Keep the home reasonably show-ready whenever possible. That can be inconvenient, particularly for families, pets, or sellers who work from home, but missed showings can mean missed opportunities.
Feedback from early showings is useful when read carefully. One buyer's objection may simply be personal preference. Repeated comments about price, condition, layout, or traffic should be taken seriously. If showings are plentiful but offers do not come, buyers may see a value gap. If showings are limited, the issue may be price, presentation, marketing, or a combination of all three.
Weeks One Through Three: Review Offers Carefully
An offer is more than a price. The strongest offer is the one most likely to close on terms that work for you. A slightly lower offer with solid financing, a realistic inspection period, a flexible possession date, and fewer contingencies may be safer than a higher offer with uncertain financing or a home-sale contingency.
Review the buyer's preapproval, earnest money, requested closing date, inspection terms, appraisal language, and any request for seller-paid costs. Your next home also matters. If you need time to buy or move, a later closing or post-closing possession agreement may be worth more than a few thousand additional dollars on paper.
Multiple offers can shorten this portion of the home sale timeline, but they do not eliminate the need for careful review. Clear communication and complete documentation protect both sides and help prevent avoidable disputes later.
Weeks Two Through Six: Inspection, Appraisal, and Loan Approval
After contract acceptance, the transaction enters its most detail-heavy phase. The buyer typically schedules a home inspection within the negotiated inspection period, often within the first seven to 10 days. Depending on the property, the buyer may also order radon, pest, sewer, well, septic, or specialized inspections.
Inspection results do not automatically mean the seller must repair every item found. Most homes, including well-maintained ones, have inspection findings. The question is whether the issue is significant, safety-related, or likely to affect the buyer's decision or financing. The response may be a repair, a credit, a price adjustment, or a decision to hold firm when the request is not reasonable.
The appraisal usually occurs after the lender orders it. If the appraised value supports the contract price, the loan can continue through underwriting. If it comes in low, the parties may renegotiate price, challenge the appraisal with relevant comparable sales, increase the buyer's cash contribution, or end the contract if no solution is reached.
Meanwhile, the lender verifies income, assets, insurance, and other buyer documents. Title work confirms ownership, identifies liens or legal issues, and prepares the closing documents. Sellers can help keep this phase moving by responding quickly to requests for payoff information, estate or trust paperwork, HOA records, or clarification about past improvements.
What Can Extend the Sale Timeline?
Some delays are predictable. Others appear only after a contract is signed. A direct, responsive agent can help identify issues early, but no one can guarantee a completely friction-free closing.
The most common timeline extensions include:
- Buyer financing that needs additional underwriting documents or a revised loan approval.
- Inspection findings that require contractor estimates, repairs, or further evaluation.
- A low appraisal that requires new negotiations or added buyer funds.
- Title issues, such as an old lien, probate question, boundary concern, or missing release.
- A buyer who must sell another home before they can complete the purchase.
The best protection is not assuming a delay means the sale has failed. It means addressing the issue promptly, keeping deadlines visible, and making decisions based on the facts of the transaction.
The Final Week: Closing and Possession
In the days before closing, complete agreed repairs, save paid invoices, arrange utilities, confirm moving plans, and remove belongings according to the contract. The buyer usually completes a final walkthrough shortly before closing to confirm the home is in the agreed condition and that negotiated repairs are complete.
Closing day involves signing documents, transferring funds, recording the deed, and confirming possession. In many Ohio transactions, keys are released once the deed has recorded and the contract's possession terms have been met. Do not assume you can leave items behind or remain in the home after closing unless that arrangement is clearly documented.
If you are buying another home at the same time, build a little breathing room into the plan when possible. Coordinated closings can work well, but a delayed lender approval on one side can affect both moves. Temporary storage, a short-term rental, or a negotiated possession period may provide valuable flexibility.
A clear home sale timeline starts with realistic expectations and stays on track through prompt decisions. Richard Tebbe helps Greater Dayton sellers plan each stage around their property, neighborhood, and next move, so the process feels organized rather than rushed.